OUTSIDE COUNSEL & SPEND MANAGEMENT
How Legal Tech Pricing Changes From Individual Users to Enterprise Plans
Share article
Overview
Legal software rarely keeps one price tag for long. A tool that starts as a £20-a-month subscription for a solo lawyer can end up, a year later, as a six-figure enterprise contract covering hundreds of users across legal, procurement and finance. The jump between those two points is not random. It follows a pattern that shows up across the legal tech market, whatever the product does.
This report sets out that pattern using data compiled by DreamLegal Market Intelligence. It covers how pricing is structured at each stage of adoption, the main commercial models vendors use, and what the data shows about how openly legal tech companies publish their prices. Where the source data does not disclose a figure, this report says so directly rather than estimating one.
1. The Three Stages of Legal Tech Buying
Almost every legal tech vendor moves customers through the same three stages: an individual plan, a team or department plan, and an enterprise agreement. What changes between them is not just the price. It is who buys, how they buy, and what they are actually paying for.
Dimension | Individual plan | Team plan | Enterprise agreement |
Buyer | Individual professional | Department or team manager | Legal, IT, procurement, finance |
Purchase method | Self-service | Assisted sale or online checkout | Negotiated procurement |
Pricing basis | User or basic usage | Seats plus pooled usage | Platform, users, usage, services |
Contract term | Monthly or annual | Usually annual | Annual or multi-year |
Support | Standard | Priority | Named support / customer success |
Security | Basic | Enhanced | SSO, SCIM, audit, controls, data terms |
Integrations | Limited | Standard integrations | API, ERP, CRM, identity, data warehouse |
Discounting | Minimal | Volume discounts | Volume, term, strategic, ramp discounts |
Evaluation | Trial or demo | Team pilot | Formal pilot, security review, legal review |
Main value proposition | Productivity | Collaboration | Risk, scale, governance, measurable ROI |
Table 1: How the buyer, process and value proposition shift across the three stages
The important point is the bottom row. At the individual level, the customer is buying personal productivity. At team level, they are buying a shared way of working. At enterprise level, they are buying a reduction in risk, plus scale and governance they can prove to their own board. A vendor that prices every stage the same way, as if it were still selling productivity software, tends to under-charge its best customers.
2. Stage 1: Individual and Self-Service Pricing
Individual plans exist to remove friction. A solo lawyer, consultant or student should be able to sign up and start using the product without talking to a salesperson. The data shows this stage typically includes:
• Publicly listed pricing, so the buyer never has to ask
• Monthly or annual billing, paid by credit card
• A single user, with little or no administrative control
• Limited storage, usage caps, or a restricted number of AI queries
• Standard support, usually email or a help centre, not a named contact
This stage is common for legal research tools, document automation software, AI drafting and review assistants, timekeeping systems, eSignature products and practice management platforms. Vendors typically charge in one of a few ways: per user per month, per user per year, per document, per AI query or credit, per signature, or per matter. Some products offer a free tier and charge only for premium features.
What individual plans usually leave out
For an AI drafting or research tool, the individual tier commonly restricts the number of documents analysed, the number of AI queries, access to the more capable AI models, file size limits, search depth, export formats, collaboration features and how long data is retained. For a contract management (CLM) tool, the individual plan usually offers only basic contract creation, a limited set of templates, no organisation-wide reporting and no external-user access.
Vendor snapshot: individual and self-service pricing
Vendor | Individual-stage pricing model | Source detail |
Docassemble | Free, open-source | Released under the MIT licence; no purchase price |
DreamLegal | Free signup | Vendor listing opportunities available for a fee |
VetoAI | Free demo | Pricing beyond the demo is not publicly listed |
HAQQ AI | Not disclosed | No public pricing stated in the available data |
Jurisphere | Not disclosed | No public pricing stated in the available data |
Legora | Not disclosed | No public pricing stated in the available data |
DigitalXForce | Not disclosed | No public pricing stated in the available data |
Table 2: Individual-stage vendors referenced in DreamLegal Market Intelligence data
Five of the seven vendors above do not publish a price at all, even at the entry level. That is worth noting because it cuts against the usual assumption that self-service software is always openly priced. In legal tech, even the cheapest tier is often gated behind a demo request.
3. Stage 2: Team and Department Plans
Once more than one person at an organisation starts using a product, the pricing model has to account for collaboration, not just access. Team plans typically add shared workspaces, role-based permissions, shared templates, basic approval workflows, admin reporting, single sign-on, internal collaboration tools, basic API access and priority support.
The data identifies four common ways vendors structure pricing at this stage:
Model | How it works | Where it works well | Main drawback |
Per-seat pricing | Every user gets an individual licence | Frequent users, homogeneous roles, predictable usage | Expensive for occasional users; encourages account sharing |
Role-based pricing | Price varies by user type: full user, business user, requester, approver, read-only, external, admin | Products used by legal plus non-legal teams, e.g. CLM | More tiers to explain; disputes over how a user is classified |
Seat-plus-usage pricing | A base number of seats plus usage allowances such as AI credits, documents reviewed or eSign transactions | AI-enabled products where infrastructure cost varies by use | Buyers dislike unpredictable bills unless usage is capped |
Workspace or department pricing | The vendor charges for the department or practice group as a whole, not per login | Vendors wanting to avoid seat-by-seat negotiation | Can undercount real usage if the workspace grows quickly |
Table 3: The four team-level pricing structures identified in the market data
Role-based pricing is described in the data as often better suited to contract management tools specifically, because a sales or procurement employee may need to submit and approve a contract without ever needing the legal drafting tools a lawyer uses. Charging that procurement employee the same rate as a lawyer tends to slow adoption rather than speed it up.
4. Stage 3: Enterprise Agreements
Enterprise pricing is where the model stops being a price list and becomes a negotiated package. According to the data, this is also the stage where pricing transparency drops to close to zero.
Vendor snapshot: enterprise-stage pricing disclosure
Vendor | What the data shows |
CoCounsel Legal | Plans available through sales contact only; no public pricing detail |
VetoAI | Free demo offered; pricing not publicly listed |
Legora | Pricing not stated in the source data |
Jurisphere | Pricing not available in the source data |
DigitalXForce | Pricing not available in the source data |
Harvey AI | Market reporting describes pilots and organisational rollouts (including at Macpherson Kelley and GE Aerospace) but does not disclose commercial pricing |
Table 4: Enterprise-stage vendors referenced in DreamLegal Market Intelligence data
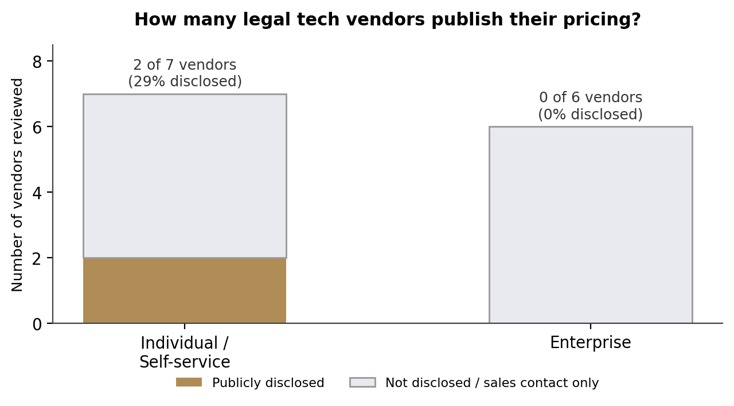
Chart 1: Across the vendors reviewed, pricing transparency falls as deployment scale rises. None of the six enterprise-stage vendors in the data publish a price.
This matters for buyers running a procurement process. If a vendor's enterprise pricing is never published, budget benchmarking has to come from peer conversations, analyst data such as this report, or the negotiation itself, not the vendor's own website.
What an enterprise agreement usually includes
The data lists thirteen components that typically appear in an enterprise legal tech contract:
• Minimum annual contract value
• Annual or multi-year commitment
• Minimum number of users or business units
• Included usage allowance
• Overage rates for usage above the allowance
• Implementation fees
• Premium support
• Security and compliance commitments
• Integration requirements
• Renewal protections
• Data-processing terms
• Service-level commitments
• Customer success resources
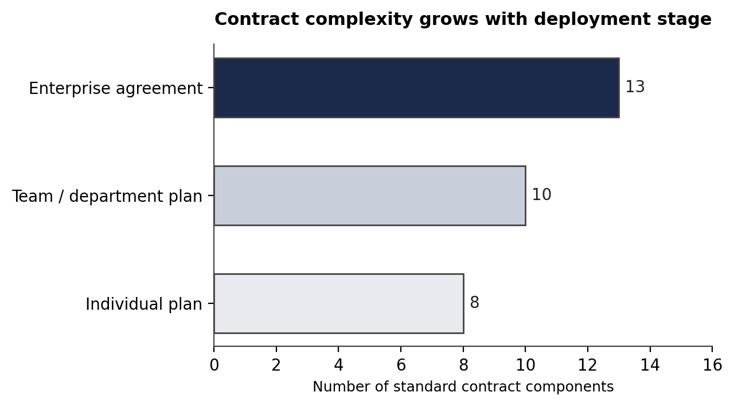
Chart 2: The number of standard contract components roughly matches the number of standard components at each stage, based on the characteristics listed in the source data (individual: 8, team: 10, enterprise: 13).
An enterprise buyer is not paying for extra logins. They are paying for reduced legal and compliance risk, standardised processes, faster turnaround, a centralised data repository, auditability, predictable support, integration into existing systems and organisational governance.
5. The Main Pricing Models Used Across Legal Tech
Stepping back from the three buying stages, the data groups legal tech pricing into eight recurring commercial models. Not every vendor uses all eight; most combine two or three.
5.1 Per-user or per-seat pricing
Each licensed user is charged individually. This is the easiest model for a buyer to understand and the easiest for a vendor to forecast, which is why it remains common in legal research, timekeeping, matter management and drafting tools. Its main weakness is that it penalises organisations with a lot of occasional users, such as business stakeholders who log in only to approve something. It can also encourage password sharing, which damages data quality.
5.2 Tiered seat pricing
Vendors sell the same seat at different price points depending on the feature set attached to it, commonly labelled Basic, Professional, Business and Enterprise. The data sets out how features typically expand across those tiers:
Capability | Basic | Professional | Enterprise |
Core document / matter management | Yes | Yes | Yes |
Collaboration | Limited | Yes | Yes |
Advanced automation | Limited | Yes | Yes |
AI features | Limited | Expanded | Custom or pooled |
Integrations | Few | Standard | Advanced / API |
Single sign-on | Sometimes | Often | Yes |
Audit and governance | Basic | Enhanced | Advanced |
Support | Standard | Priority | Dedicated |
Analytics | Basic | Expanded | Custom |
Table 5: How feature access typically expands across tiers
The data is clear that this only works if each tier reflects a genuine difference in value. If the extra features in a higher tier are minor, buyers notice and the upgrade path stalls.
5.3 Role-based pricing
Different job functions pay different rates: full professional user, lawyer, paralegal, legal operations user, business requester, approver, read-only user, external collaborator, administrator. This is common in CLM, matter management and legal operations platforms because it lets a vendor sell across an entire organisation without charging every participant the full professional rate. The trade-off is a more complicated sales conversation and, occasionally, disputes over which category a given employee belongs in.
5.4 Usage-based pricing
Price is tied to measurable consumption: AI prompts or credits, documents analysed, pages reviewed, contracts generated, redlines created, eSign transactions, data volume, storage, API calls, or, for compliance products, the number of entities and jurisdictions monitored. The data breaks out how this applies by category:
• eDiscovery: data volume, gigabytes processed, hosted data, number of custodians, review pages
• eSignature: envelopes, documents sent, signers, authentication method, API transactions
• Legal AI: AI credits, documents reviewed, pages analysed, advanced-model usage, generated outputs
• Regulatory compliance: legal entities, jurisdictions, regulations monitored, business units, filings, alerts
Usage pricing aligns cost with consumption and gives smaller customers a lower entry point, but enterprise legal buyers generally dislike an unpredictable bill. The data notes that vendors improve acceptance by offering annual usage pools, consumption alerts at set thresholds (for example 50%, 75% and 90%), pre-agreed overage rates and the ability to carry unused usage forward.
5.5 Per-matter pricing
Common in litigation management, claims platforms, investigations and immigration case work, this model charges based on the number of active matters or cases. It is easy to explain in litigation contexts and ties directly to customer activity, but it creates two problems: customers may close matters early to control cost, and a single complex matter can consume far more resource than several simple ones, which makes revenue harder to predict unless the vendor introduces matter tiers.
5.6 Per-document or per-transaction pricing
Used for contract generation, document automation, eSignature, legal notices and filings, this model charges per document, per contract reviewed, per signature envelope, per filing or per page. It suits clearly transactional use cases but works poorly for a product meant to become a daily operating system, since customers may reduce usage simply to hold down cost.
5.7 Platform or workspace pricing
A fixed annual fee covers the core application, administration, security, the central repository, standard workflows, reporting, basic support and standard integrations. Additional charges apply on top for more users, extra modules, higher usage, premium AI models or advanced analytics. The data describes this as one of the strongest models for a broad enterprise platform because it gives the buyer a predictable base cost while still letting the vendor charge more for heavier use.
5.8 Modular pricing, professional services and negotiated enterprise agreements
The remaining three models named in the data are modular pricing (charging separately for distinct product modules), professional services and implementation fees, and fully negotiated enterprise agreements of the kind set out in Section 4. The source data does not provide further structural detail on the first two beyond naming them as recognised models in the market.
Was this update helpful?
Continue reading
Related articles
Outside Counsel & Spend Management
NuCAS Lands Ex-DWF Managed Services Chief as Investor and Board Adviser
Read article
Outside Counsel & Spend Management
Kyra Law Passes AI Cost Savings Directly to Startup Clients, Challenging Big Law Pricing
Read article
Outside Counsel & Spend Management
BigHand Acquires Ayora, Expanding AI Footprint in Legal Pricing
BigHand has acquired Ayora, the legal AI pricing specialist, in a transaction announced August 4, 2026, quickening BigHand's move into AI-enabled commercial intelligence for law firms.
Read articleStay informed
Make your next legal technology decision with more clarity.
Join DreamLegal for independent research, market perspectives, and practical evaluation guidance for legal teams.
Create Free Account